Whether GCC governments should create strategic lubricant reserves is, first, a question about how modern supply shocks behave. In 2026, the IEA described renewed attacks and diplomatic gridlock that “continued to hamper the normalisation of oil flows,” with world oil supply projected to average 100.7 mb/d in 2026, down 5.7 mb/d year-on-year, and with a full recovery in supplies from Middle East producers deferred until 2027. Lubricants are not the same as crude, but they depend on base oils and refinery-linked logistics. The 2026 disruption highlights a planning reality: if feedstocks, refining activity, and product availability are hit at the same time, the hardest problem is physical continuity, not just price volatility.
The clearest 2026 signal is that emergency buffers matter most when inventories are already depleted. A market commentary citing EIA data described a 7.2-million-barrel weekly fall in US commercial crude stocks to 404.5 million barrels, which it said was 6% below the five-year seasonal average, while the US Strategic Petroleum Reserve (SPR) declined by 3.8 million barrels to 307.7 million. It also noted that onshore stocks can be drawn relatively quickly, while crude held at sea may take weeks to reach destination. For a GCC discussion about resilience, this timing gap is the operational lesson: if the supply chain is stressed, the most valuable reserves are those that can be accessed and converted into usable products fast, with clear rules for release and replenishment.
Crude Reserves Exist — but Product Coverage Is the Clue for Lubricants
One reason “strategic lubricant reserves GCC” is now a serious policy idea is that crude-focused reserves do not automatically solve product shortages. The IEA’s coordinated action on 11 March 2026 agreed a release of 400 million barrels; when contributions were confirmed on 19 March, they totalled 426 million barrels. Importantly for any lubricant parallel, Global Oil Shock notes that only 125 million barrels were refined products, versus 301 million barrels of crude. It also quotes the IEA’s purpose statement: releases are meant “to mitigate the negative economic impacts of a supply shock, and not as a tool to manage prices.” For GCC governments considering lubricant reserves, that distinction points to design priorities: target continuity of supply for critical sectors, and decide what form of stocks best bridges a real physical gap.
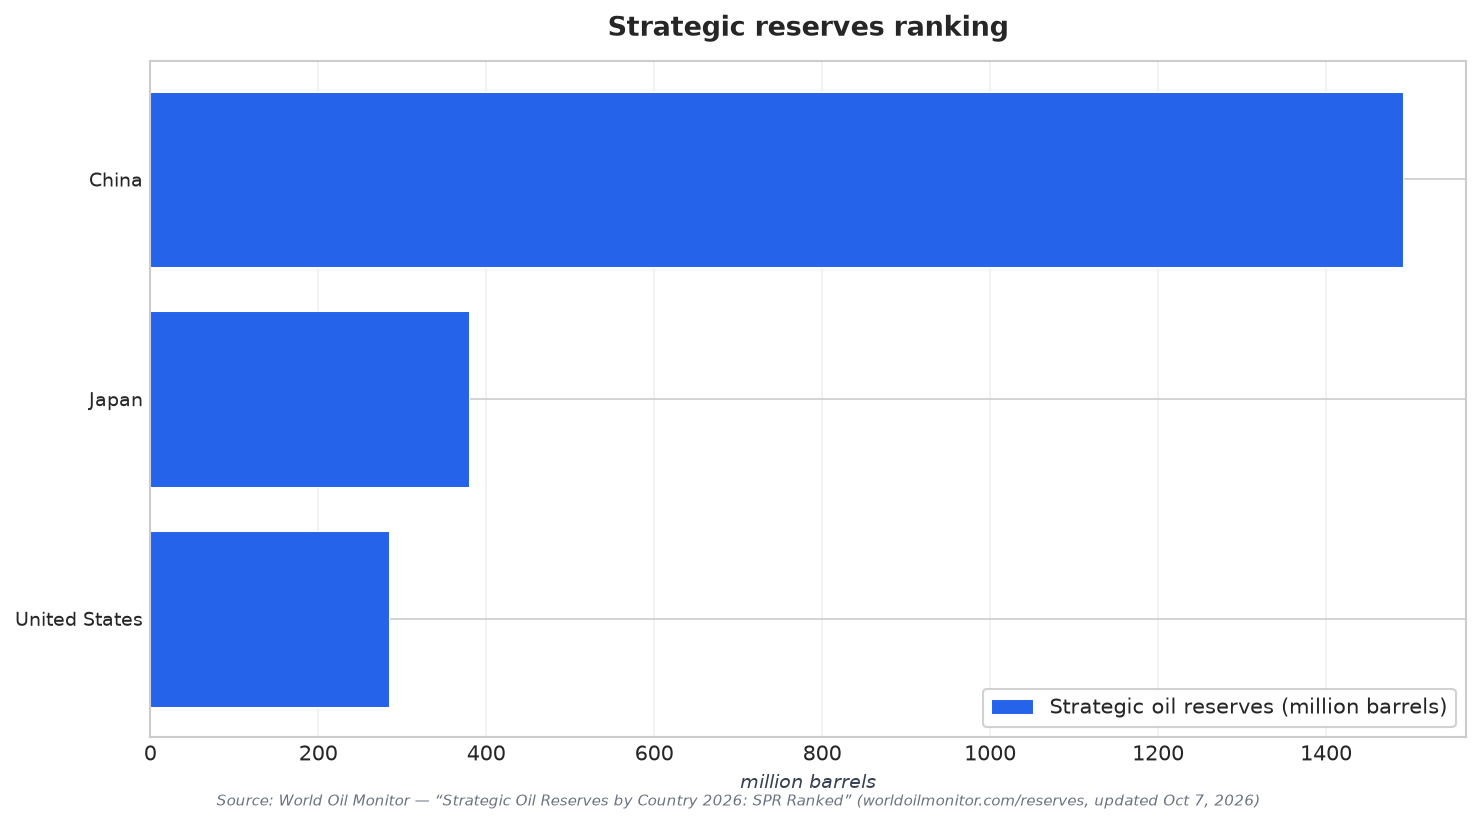
The scale and management of strategic stocks also show the trade-offs. World Oil Monitor estimates that among 11 tracked countries, the largest crude stockpile is China’s at about 1,492 million barrels (not officially disclosed), followed by Japan at 380 Mb and the United States at 283.8 Mb, with all 11 together holding roughly 2,785 million barrels. In the US, the SPR fell to 283.8 million barrels in the week ending Sep 25, 2026, described as the lowest level since October 1982 and down 131.7 million barrels (32%) from 415.4 million on Mar 20, 2026. The same source notes the US delivered its IEA contribution as an emergency exchange where companies borrow crude and must return it later with additional barrels as a premium. For the GCC, the lesson is governance: stock levels can fall quickly in a crisis, so replenishment mechanics should be built in from day one.
A final lesson is that policy can be structured without a single government-owned pile of barrels, but the obligations must be explicit. Global Oil Shock reports the UK has no government stockpile and no central stockholding agency; instead, companies supplying more than 50,000 tonnes a year must hold 67.5 days of domestic net consumption, with at least 22 days as finished products (IEA). Separately, it lists example “days of cover” figures for Germany (91.7), France (87.9), and Spain (97.1) in June 2026 (Eurostat). For GCC decision-makers, these models suggest a menu of options: public reserves, industry obligations, or hybrids. The 2026 shock reinforces that whatever model is chosen for lubricant resilience should be measured in usable product coverage, with rapid accessibility and clear release rules aligned to economic impact mitigation.
What did the 2026 shock show about emergency stocks and supply disruptions?
Why is refined-product coverage relevant when discussing lubricant reserves?
How fast can inventory tightness amplify a crisis?
What governance lesson applies to strategic lubricant reserves in the GCC?
How could a GCC program for strategic lubricant reserves be structured without a government-owned stockpile?