Scenario planning for Middle East lubricant demand starts with the same chokepoints that hit fuels and feedstocks. The IEA notes that traffic through the Strait of Hormuz has been essentially halted by the conflict, and it frames the Gulf as a key source of refined oil product exports, notably middle distillates such as diesel and jet fuel. Those products matter because they support freight, aviation, construction, and industrial activity that tends to pull lubricant consumption with it. In August 2026, the IEA also cut global oil demand expectations for 2H26 by roughly 550 kb/d versus the prior month as the continuing closure of Hormuz disrupted international supply chains and curtailed product availability.
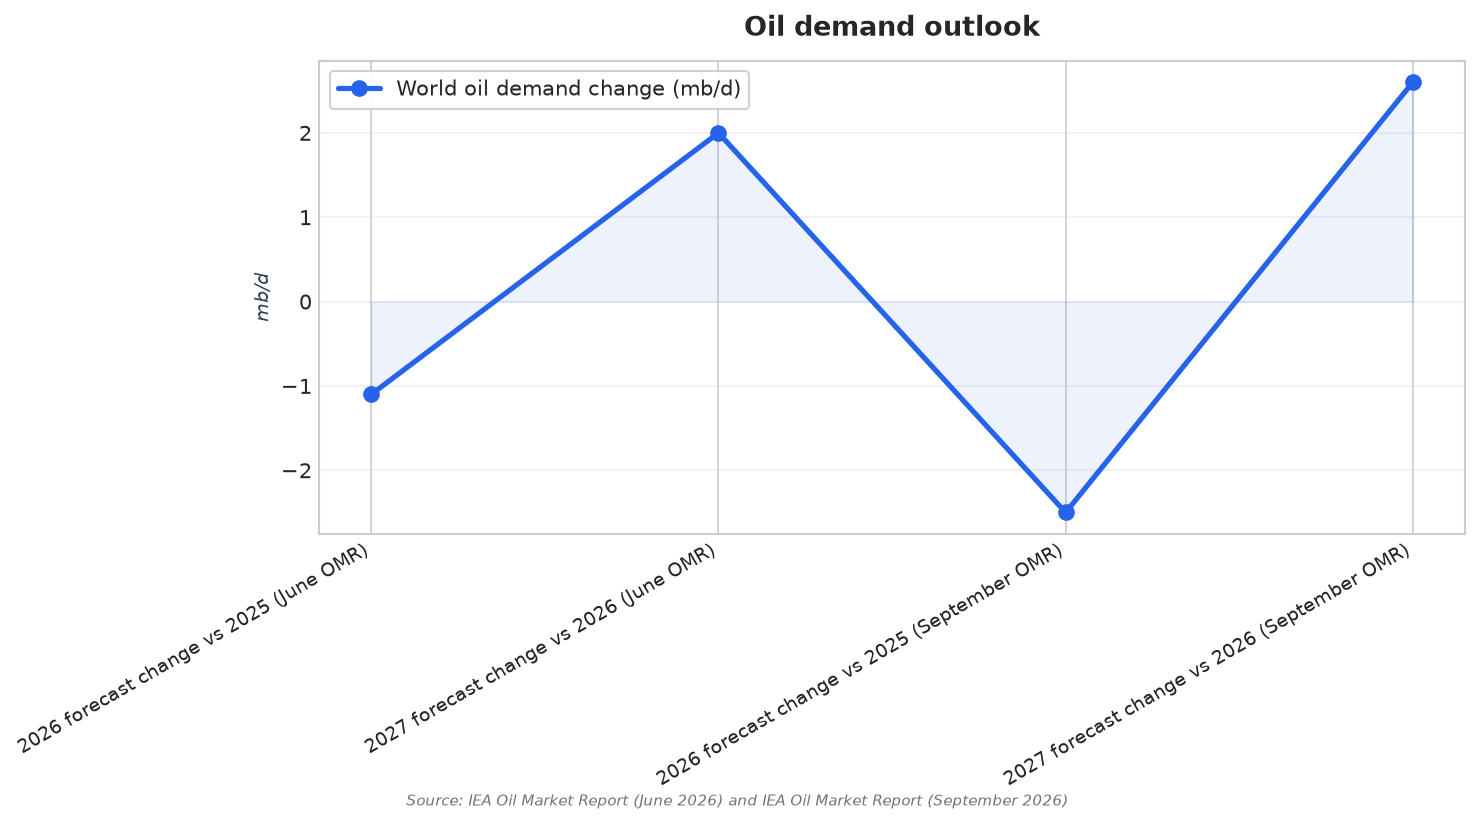
The depth and duration of disruption are visible in global supply, runs, and inventories. In June 2026, the IEA forecast global oil demand to decline by 1.1 mb/d y-o-y in 2026 after 2Q26 deliveries plunged by 5 mb/d y-o-y, with growth rebounding to 2 mb/d in 2027. But by September 2026, the IEA forecast a steeper 2.5 mb/d decline for 2026, with recovery of 2.6 mb/d in 2027, as negotiations delays pushed normalisation into next year. Refining signals also matter for base-oil and blending economics. The IEA forecast global refinery throughputs to decline by 2.5 mb/d on average in 2026 and rebound by 3.5 mb/d in 2027, while observed inventories drew heavily, reaching cumulative draws since February of 507 mb by August.
Three Recovery Paths to Stress-Test 2028 Lubricant Demand
Path 1: Fast normalisation (ceasefire holds and flows restart). This path assumes the type of diplomatic breakthrough the IEA described in June 2026, when a US-Iran interim agreement “could pave the way” for reopening Hormuz and lifting a US blockade on Iranian oil traffic, sending prices down. Under this path, refining and product trade can re-link sooner, helping lubricant demand rebuild through transport and industrial utilization. Even in this more constructive setup, planners should watch the IEA’s reminder that operational and political constraints, including prolonged demining and unresolved transit arrangements, create downside risks that can slow the return of steady product availability.
Path 2: Delayed recovery (stop-start shipping and refinery bottlenecks). Here, lubricant demand improves but remains uneven because supply chains stay fragile. In August 2026, the IEA described continued Middle East product export disruptions, seaborne product trade down 3.8 mb/d y-o-y, and diesel exports from Russia, the Middle East and Asia down 1.3 mb/d y-o-y, about 20% of global seaborne trade. July refinery runs were 80.9 mb/d, nearly 5 mb/d below year-earlier levels, and the system “elsewhere” lacked capacity to offset bottlenecks. For lubricant marketers, this path implies intermittent tightness in middle distillates and higher logistics friction, rather than a clean rebound.
Path 3: Prolonged stress (renewed attacks and extended outage risk). This path assumes security conditions keep exports and runs constrained well into the planning horizon for Middle East lubricant demand recovery scenarios 2028. In September 2026, the IEA reported that more than 10 mb/d of Gulf output remained shut in amid heightened security risks and that the expected recovery in the Gulf was deferred until 2027. Separate risk framing highlights why the Strait is so pivotal: one analysis states that major crude export terminals including Ras Tanura, Yanbu, and Jebel Ali aggregate approximately 60% of GCC crude exports through this single passage, while Saudi Arabia’s East-West Pipeline offers only 5 million barrels per day capacity. Wood Mackenzie also describes a prolonged Hormuz closure as the greatest single risk to energy markets today, reinforcing why downside planning for lubricants should remain explicit.
What variables matter most for lubricant demand recovery after the 2026 Gulf conflict?
How do IEA refinery throughput forecasts inform lubricant scenario planning?
Why is the Strait of Hormuz central to these scenarios?
How should teams use Middle East lubricant demand recovery scenarios for 2028 in practice?