
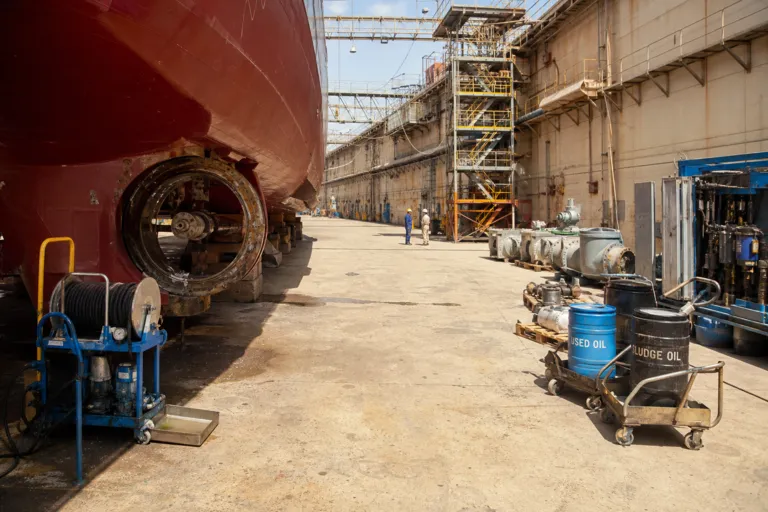
Global ship repair and maintenance spending is described as large and rising in multiple market reports, creating a stronger baseline for regional hubs, including the Gulf, to compete for repair calls. Future Market Insights values the global ship repair and maintenance service market at USD 32.0 billion in 2026 and forecasts USD 60.6 billion by 2036, at a CAGR of 6.6%. SNS Insider similarly values the market at USD 33.47 billion in 2025 and projects USD 54.40 billion by 2033, with a 6.26% CAGR for 2026–2033. These global figures do not measure Gulf activity directly, but they explain why Gulf shipyards are positioning for recurring maintenance, retrofits, and turnaround-driven work that tends to be lubricant intensive.
The demand mix matters because it signals where consumables and service kits follow repair labor. One benchmark-oriented report notes that scheduled dry docking applies to 82% of vessels every 2–5 years, while emergency repair interventions account for 18% of annual service demand in the category it describes. The same source states that deck machinery servicing represents 27% of offshore support repair contracts, highlighting a repeatable workstream where grease and hydraulic fluid selection, change-out, and contamination control are part of standard execution. In parallel, predictive maintenance integration appears in 37% of shipyards, and the report ties that shift to a 14% reduction in unscheduled downtime, which can change lubricant procurement from ad hoc purchases to planned bundles aligned to docking cycles.
Where Lubricant Opportunities Cluster: Stern Tube, Deck Machinery, and Hydraulics
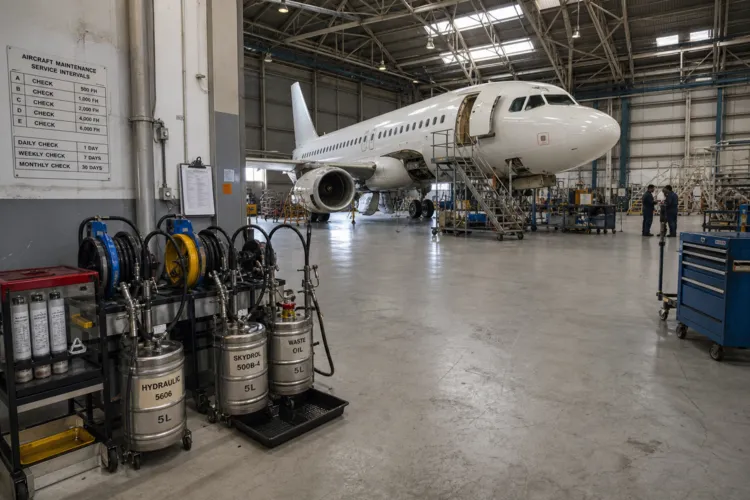
Marine lubricant demand signals are especially strong where equipment complexity and mission profiles raise fluid consumption. Mordor Intelligence notes that next-generation installation vessels equipped with dynamic-positioning thrusters and jacking systems significantly boosted consumption of stern-tube and hydraulic fluids. The same report adds that consumption of grease and hydraulic fluids increased, fueled by the growing complexity of deck machinery, even while system-oil demand declined due to fewer gearboxes from integrated electric drives. For Gulf shipyards, these statements frame practical “shipyard ship repair lubricants Gulf” opportunities around stern-tube oil management during shaftline service, hydraulic-fluid drain-and-fill during machinery work, and grease programs tied to deck equipment maintenance, especially for vessel segments that rely on thrusters, jacking systems, and heavy deck operations.
Regulatory and retrofit pressure can further concentrate work in lubricant-adjacent systems. Future Market Insights links market momentum to tightening environmental and safety regulations and specifically points to upgrades such as scrubbers, ballast-water treatment norms, fuel-efficiency enhancements, and digital monitoring systems. Another report states that emission compliance retrofits influence 33% of global fleets, and that automation retrofit services are required in 25% of vessels built before 2015, while maritime safety regulations apply to 100% of international shipping operations. These figures are global context, but they help Gulf repair planners anticipate more retrofit bundling, where lubricant specifications, compatibility checks, and commissioning support are handled alongside mechanical and control-system upgrades rather than treated as a separate afterthought.
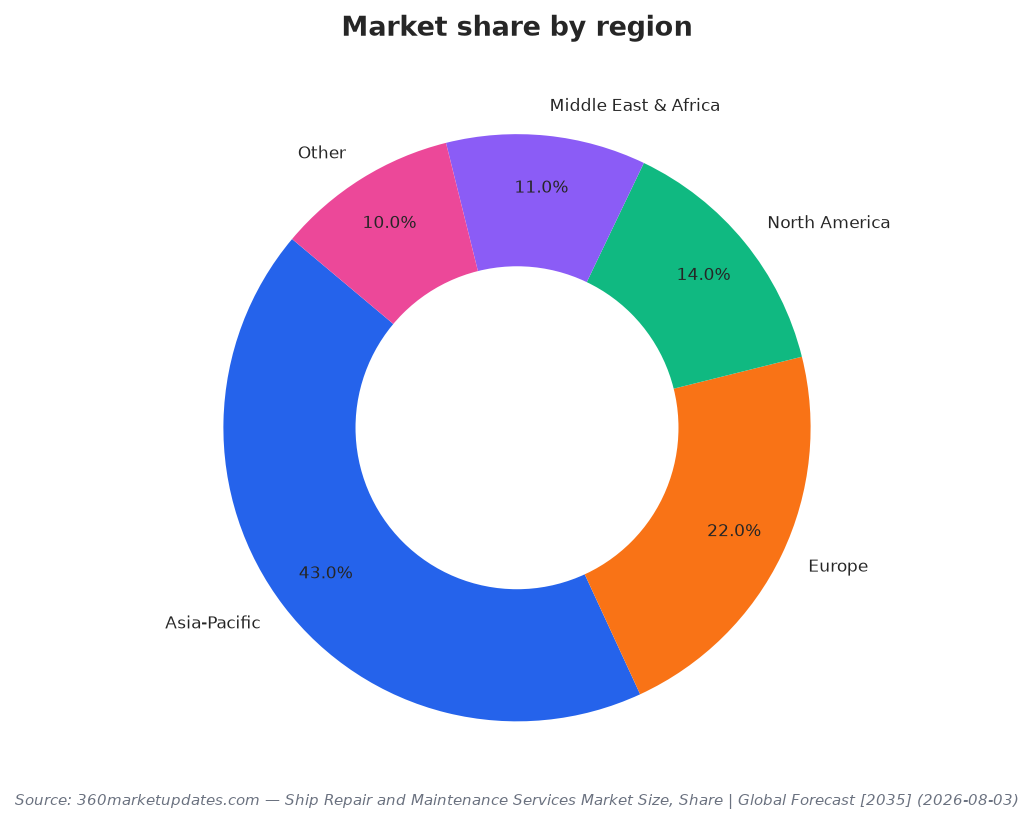
Finally, shipyard execution is shifting toward more data-driven maintenance planning, which favors suppliers that can support condition-based service and standardized product selection. The benchmark report states that digital fleet monitoring platforms are utilized by 33% of operators to optimize repair cycles within 2–5 year dry docking schedules. That same report notes dry dock utilization exceeds 80% in leading maritime hubs, and it breaks out regional market share context, including North America at 14% and the Middle East & Africa at 11% of global share. Those shares are not a direct read on Gulf shipyards alone, but they underline that competition for repair calls is international. Gulf yards that package stern-tube work, deck machinery servicing, and hydraulic lubricant programs into predictable scopes can align with the planning cadence implied by monitoring tools and scheduled docking behavior.
What do global reports say about the size and growth of ship repair demand?
How often do vessels typically follow scheduled dry docking cycles?
Why is deck machinery an important focus area for repair contractors and lubricant suppliers?
What equipment trends are linked to higher stern-tube and hydraulic fluid consumption?
How can Gulf shipyards position shipyard ship repair lubricants for stern-tube and hydraulics work?