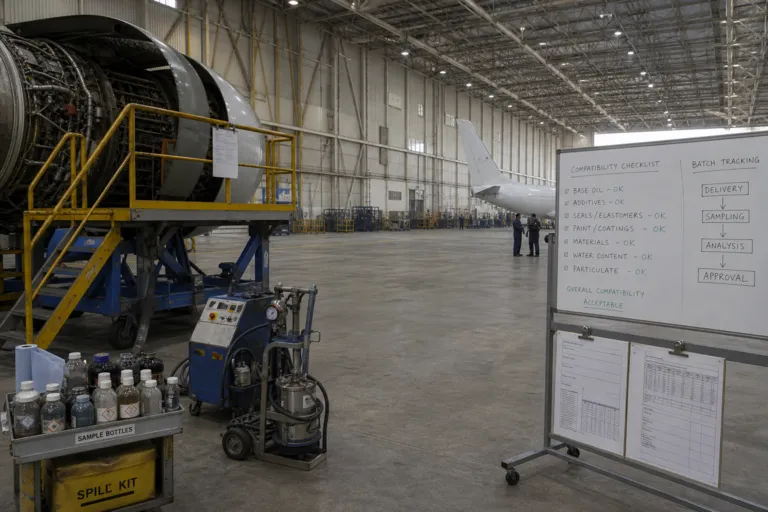
Gulf airlines and local MRO providers are being pushed toward Sustainable Aviation Fuel (SAF) decisions even when the biggest regulatory pressure is coming from other regions. Fortune Business Insights notes that the Middle East and Africa region is gradually exploring opportunities in SAF, and that aviation hubs in the Gulf are evaluating SAF supply partnerships to support airline decarbonization commitments. The same source highlights a core adoption question: compatibility with existing turbine engines used in fixed-wing aircraft. That same compatibility lens also matters for turbine engine oils, because maintenance organizations must manage what happens when fuel chemistry changes, even if the aircraft and engine stay the same.
Market signals show why airlines and their maintenance ecosystems are paying attention. Fortune Business Insights projects the global SAF market will grow from $4.02 billion in 2026 to $40.09 billion by 2034, at a CAGR of 39.95%. Precedence Research values the SAF market at USD 3.55 billion in 2026 and projects around USD 171.75 billion by 2035, with a CAGR of 54.2%. These are global forecasts, not Gulf-only outcomes, but they frame the scale of procurement change that can ripple into maintenance planning. In parallel, Mordor Intelligence estimates the aviation fuel market at USD 341.48 billion in 2026, growing to USD 548.71 billion by 2031 at a 9.95% CAGR, adding another layer of commercial pressure around fuel choices and premiums.
Why “Drop-in” SAF Still Creates Maintenance Work
iFactory writes that SAF is certified as a drop-in fuel under ASTM D1655, but also stresses that “drop-in does not mean maintenance-neutral.” It points to chemical differences that create operational implications requiring systematic tracking, specifically calling out near-zero aromatic content in HEFA-SPK fuels. For Gulf airlines and MROs, this turns the sustainable aviation fuel turbine oil compatibility topic into a documentation and configuration-control problem as much as a technical one. When blend ratios, pathways, and supply sources vary by route and station, maintenance teams need consistent records to support decisions and audits, rather than relying on assumptions that a certified fuel has no downstream effects.
Regulations elsewhere are already defining timelines that can affect Gulf carriers operating international networks and working with global lessors and OEM-aligned MRO standards. iFactory states 2025 is the first year of binding SAF mandates in the EU and UK, and it lists ReFuelEU Aviation requirements starting at 2% in 2025, rising to 6% by 2030 and 70% by 2050. The UK SAF mandate is described as requiring 2% in 2025, climbing to 10% by 2030 and 22% by 2040, with HEFA fuels capped at declining percentages from 2026 onward. It also notes CORSIA Phase 1 (2024-2026) is voluntary with 129 participating states, and Phase 2 (2027-2035) becomes mandatory for all ICAO member states. Even when obligations fall on suppliers or operators, MROs face the “track, report, and verify” workload to evidence what was used and when.
Compatibility questions are also shaped by what SAF pathways dominate near-term supply. Fortune Business Insights describes many current SAF pathways as relying on waste oils, animal fats, and agricultural residues, while Stratview Research notes HEFA-based biofuels made from used cooking oil and animal fats are already certified and in commercial use. Precedence Research similarly describes the HEFA-SPK sector as producing the majority of commercially available biofuels and using vegetable oil that is oxygenated and then hydrogenated to decompose lipid compounds into hydrocarbons. For Gulf airlines building supply partnerships, the practical takeaway is to align fuel pathway data, blend tracking, and maintenance records so that engine and oil-related observations can be tied back to the specific fuel history at the tail-number level.
What does “drop-in” SAF mean for turbine engines, and why does it still matter for oil compatibility?
Which mandates are already setting SAF blend timelines that MROs must be ready to document?
Are Gulf aviation hubs actively considering SAF, or is this only a Europe and U.S. story?
What do the sources say about the scale of the SAF market growth driving these operational questions?
How should an MRO frame sustainable aviation fuel and turbine oil compatibility without over-claiming technical effects?